7 House Flipping Mistakes to Avoid
House flipping mistakes usually start with bad numbers: thin rehab budgets, ignored holding costs, inflated ARV, and deals you force just to get started.

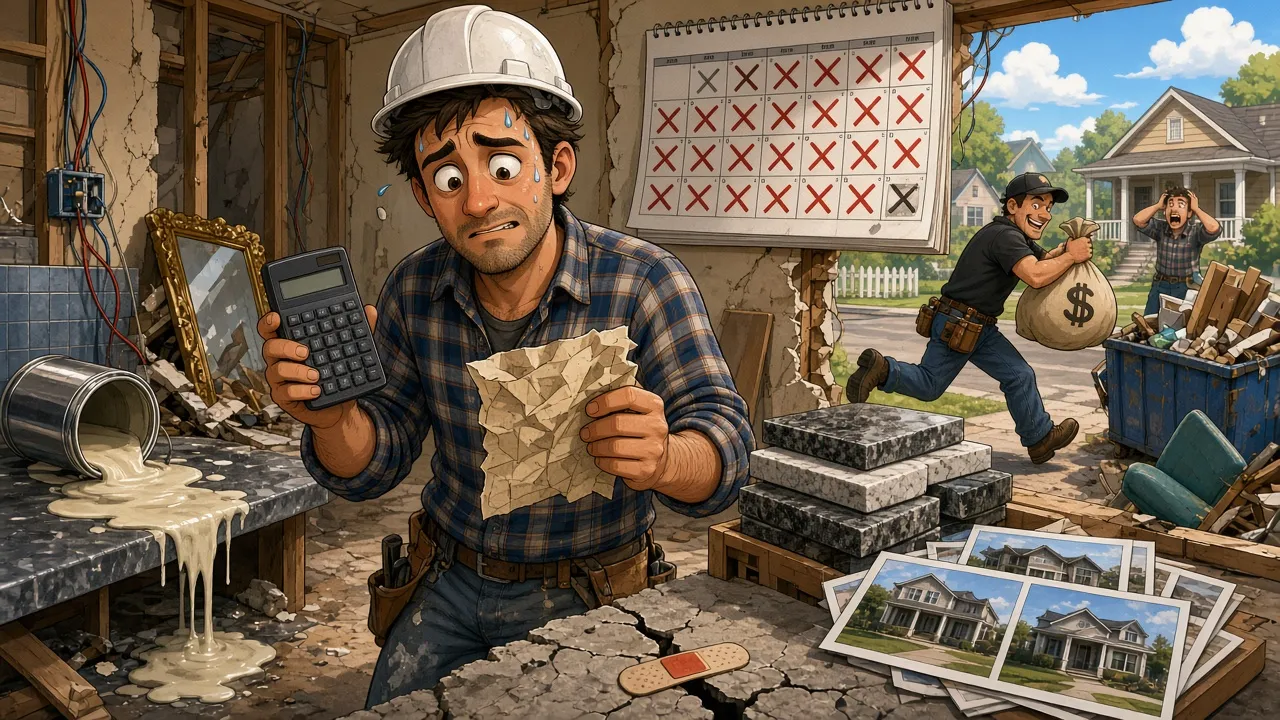
The biggest house flipping mistakes usually happen before a hammer swings. Bad rehab numbers, thin reserves, a rushed timeline, or a weak purchase can wipe out a first (or second) flip even when the finished house looks great.
As a hard money lender at Best Lending Co, I see these patterns on files across California, Massachusetts, North Carolina, and Virginia. Paint colors are not what sinks the deal. The spreadsheet is.
If you are about to write an offer, pressure-test the purchase, rehab, timeline, and exit before you commit. Financing only helps when the deal itself is real.
Mistake 1: Why Do Flippers Underestimate Rehab Costs?
Flippers underestimate rehab when they misread the scope or shrink the budget just to make a purchase price work.
Sometimes it is inexperience. A crack in the ceiling looks like paint. It might be foundation. Sometimes it is intentional. You and the seller are $5,000 apart, so you tell yourself the renovation can come in $5,000 cheaper instead of renegotiating the offer. That almost always comes back later as change orders, extra interest, and a thinner exit.
The renovation number is the renovation number. Stick to it when you offer. Sometimes the best deal is the one you do not do.
- Line-item the scope Price kitchen, baths, roof, HVAC, electrical, plumbing, and exterior separately. A lump sum hides the misses.
- Add contingency Plan on 10% to 15% over your contractor quote on a first or early flip.
- Do not shrink rehab to win the bid Cut the purchase price, not the work the house actually needs.
- Get multiple bids One quote is a data point. Three quotes are a market check.
Mistake 2: What Holding Costs Do Investors Forget?
Investors forget the money cost of owning the house while it sits: loan interest, insurance, utilities, dumpsters, toilets, HOA, and taxes.
A hard money file that only budgets the down payment is incomplete. If the loan covers most of the purchase and rehab, you still need cash for monthly carry. On many flips, that is roughly $1,500 to $3,000 per month, depending on loan size and local taxes. Scale too fast without reserves and you start using one project’s money to finish another. That is how people go broke with “busy” pipelines.
At Best Lending Co, I want liquid reserves covering six months of interest-only payments plus about 20% of rehab. You do not pay interest on undrawn rehab funds, which helps if you stage the work. You still pay for every month the house is yours.
Never rely on one house selling on time so you can fund the next one.
Mistake 3: Why Does Underestimating Timeline Kill Profit?
Underestimating timeline kills profit because every extra week adds hold cost, and a late listing can hit the worst selling season in your market.
New investors trust a contractor who quotes what they want to hear. Experienced investors sometimes shrink the calendar to make holding costs look smaller on paper. Either way, the house takes longer than the spreadsheet.
A rough rule from operators who track production: if a $45,000 rehab normally takes about three months, plan roughly one month per $15,000 of renovation until you have your own track record. Then add buffer for permits, inspections, and a slow sale.
A typical U.S. flip in early 2026 took about 165 days from purchase to resale, according to ATTOM. If your model assumes 90 days because you are impatient, the gap comes out of your pocket.
Re-run the deal at your planned hold plus 60 to 90 days. If profit disappears on a normal delay, the purchase is too high.
Mistake 4: How Do Flippers Overestimate ARV?
Flippers overestimate ARV when they ignore comps, ignore location flaws, or assume the market will keep rising until they list.
Unintentional version: you compare a busy-street house to a cul-de-sac sale. Intentional version: the last few flips sold hot, so you tell yourself this one will beat comps by $20,000. Then the market cools, rehab runs over, and the “deal” barely breaks even.
Base ARV on sold comps from the last 90 days to six months, not on what you hope the house will be worth when you finish. Match bed count, size, finish level, and micro-neighborhood. Unfixable problems (traffic, power lines, weird floor plans) need a haircut, not optimism.
Use our Max Offer Price Calculator to work backward from a conservative ARV before you write the offer.
Mistake 5: Why Is Overdoing the Rehab So Expensive?
Overdoing the rehab is expensive because buyers will not pay above the neighborhood ceiling just because your finishes are nicer.
If comps sell with laminate, granite does not automatically raise the sale price. It raises your cost. New investors do this out of excitement. Experienced investors do it when they trust their brand more than the comps. The result is the nicest house on the block that still sells near the highest recent sale, not above it.
Renovate to what buyers in that street already pay for. The comps set the finish level. Your taste does not.
Mistake 6: What Happens When You Hire the Wrong Contractor?
Hiring the wrong contractor can wipe out more cash than a bad paint choice ever will, especially if you fund a huge deposit before work is done.
The pattern is familiar. You hire the first person who can start Monday. Or you skip references because you are eager. Or you keep working with someone you trust even after money problems show up. I have seen investors hand a trusted contractor a large deposit, then lose contact within days and have to explain a five-figure hole to their capital partner.
I will not fund a file that depends on hope and a handshake. Protect yourself the same way:
- Get multiple quotes before you pick a GC
- Verify licenses, references, and recent jobs you can walk
- Avoid giant upfront deposits; prefer progress payments tied to completed work
- Use a hard money draw process so funds release after work is verified
On our fix and flip loans, rehab draws are typically reviewed quickly and wired within 24 hours after approval. That structure exists so you are not wiring half the job to someone who has not earned it yet.
I have seen trusted-contractor deposits vanish before work starts. Due diligence is cheaper than chasing the money later.
Mistake 7: Why Is Closing on the First House So Risky?
Closing on the first house that falls in your lap is risky because excitement replaces underwriting. A realtor or wholesaler calling it a deal does not make it one.
New investors want the first flip on social media. They buy the “up and coming” street because it feels sexy, ignore thin margins, and spend six months renovating a house that sells for basically free after costs. The discipline is the opposite: find reasons the house is not a deal, then only proceed if the numbers still survive.
Have someone else check the file:
- A contractor on rehab cost and timeline
- An agent on resale and days on market
- Me on leverage, reserves, and whether the exit supports the loan
For first-time fix and flip leverage, plan on up to 87.5% of purchase plus 100% of rehab, a loan capped around 70% to 75% of ARV, rates typically 9% to 11%, and roughly $30,000 to $50,000 out of pocket on a mid-size deal plus reserves. If the only way the deal works is perfect execution, it does not work.
Related reading: how to flip houses with no money or experience.
How Should You Pressure-Test These Seven Before You Offer?
Pressure-test all seven by running conservative comps, a line-item rehab, full holding costs, a slower timeline, and a contractor plan before you go under contract.
Send me:
- Address and purchase price
- Three to five sold comps supporting ARV
- Rehab budget with major line items and contingency
- Target close date and vacancy status
- Your liquidity, approximate credit, and exit plan
Then run the full picture in our Fix and Flip Profit Calculator. If it only pencils when everything goes right, walk.
Frequently Asked Questions
What are the biggest house flipping mistakes?
Buying wrong and budgeting wrong. Most losses come from inflated ARV, light rehab numbers, ignored holding costs, or forcing a deal before the math works. The jobsite problems usually show up after those mistakes are already locked in.
How much contingency should I add to a rehab budget?
Plan 10% to 15% over a solid contractor quote on early flips. First-time scopes often run higher than a walkthrough estimate once systems are opened up.
Should I give a contractor a large deposit?
Be extremely careful. Large upfront deposits are where investors lose the most cash the fastest. Prefer multiple bids, verified references, and progress payments or lender draws tied to completed work.
How do I set a realistic ARV?
Use sold comps from the last 90 days to six months in the same micro-neighborhood, matched for size, beds, baths, and finish level. Do not bank on the market rising while you renovate.
Can Best Lending Co fund a first-time flipper who avoids these mistakes?
Yes. First-time investors can qualify. A conservative deal, 650+ credit (680+ for better terms), and enough liquidity still matter. I would rather kill a weak offer early than fund a file that only works on paper.
Have an address and want a second set of eyes before you close?
Send me the comps and rehab budget or start with our Fix & Flip Profit Calculator. No pressure. Just a real purchase, rehab, ARV, and hold before you commit.
Avoid the seven mistakes on paper, and the first flip gets a lot less expensive.